FARGO, N.D., September 21, 2026 — Border States has published the following supply chain update.
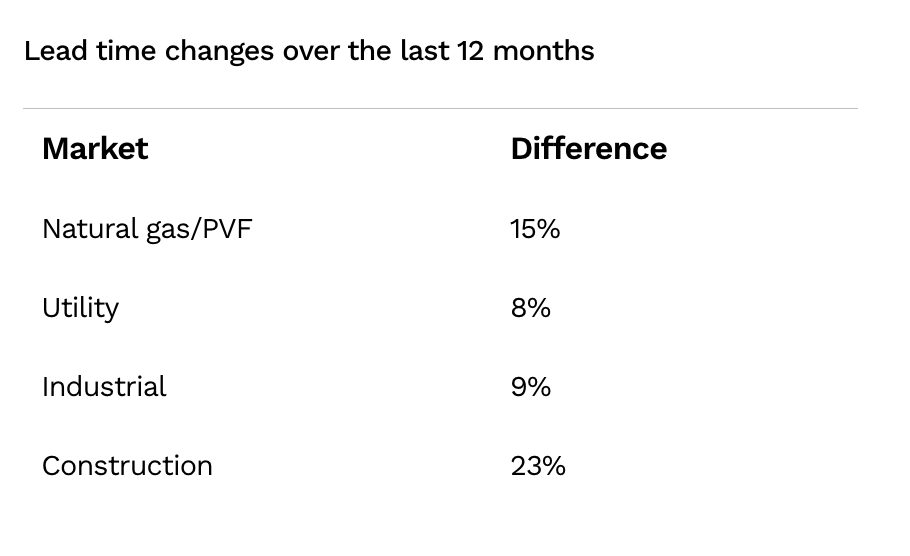
Lead Time Trends
U.S.-Canada trade actions escalate
After a three-day pause and unsuccessful negotiations, the United States implemented an additional 50% tariff on certain Canadian goods under Section 338, escalating trade tensions between the two nations.
Review of recent U.S.-Canada trade actions:
- August 22: The United States’ three-day pause expires and an additional 50% tariff on certain Canadian goods under Section 338 takes effect regardless of a covered product’s United States-Mexico-Canada Agreement eligibility.
- September 8: Canada’s reciprocal tariffs, ranging between 15% and 50% on select U.S. goods, including steel products, appliances and electronics, take effect.
- September 15: The United States removed certain products, including rock salt and cement, from the existing Section 338 tariffs and replaced them with other products, such as all-terrain automobiles and additional dairy products.
- Tuesday, September 29: Separate U.S. import bans on certain Canadian goods, such as alcohol and dairy, take effect.
Why it matters: The impact of active tariff policies is increasingly determined at the product level rather than by broad tariff announcements. For our core markets, the practical effect will depend on the products being purchased, where they are sourced and how they move through North American supply chains.
Zoom in: Product categories with close ties to Canada include utility poles, lighting and lighting controls. Customers purchasing Canadian-origin products, or products that rely on Canadian inputs, should pay close attention to country of origin, product classification, quote validity and supplier communications.
August job report surpasses market expectations
The U.S. labor market showed improvement in August after a weaker July, which helped ease some concerns that emerged after July’s employment report.
Zoom in: Employment gains came in manufacturing and construction, while the information and finance sectors lost jobs.
- The economy added 162,000 jobs in August, up from a revised gain of 21,000 in July, and surpassed market expectations.
- The unemployment rate remains unchanged at 4.1%, a historically low level that indicates the labor market remains generally healthy.
- Labor force participation rate rose to 61.6% from 61.4% last month.
- Average hourly earnings increased 0.3% from July and increased 3.1% year over year, just above 3% forecasts.
Why it matters: For our markets, manufacturing and construction hiring remains supportive of ongoing infrastructure, industrial and project activity. Hiring in critical sectors, such as construction, manufacturing and transportation, can directly affect project execution, installation schedules and supply chain performance. Wage growth remains an important indicator because it influences both customer demand and supplier cost structures.
Key takeaway: The labor market appears stable heading into the fourth quarter, but conditions are likely to remain uneven across industries and regions.
The Federal Reserve voted to raise the federal funds target range by a quarter-point to 3.75%–4%, as expected. The previous range was 3.5%–3.75%. This is the first rate hike since 2023. Inflation remains elevated amid the energy shock from conflict in the Middle East.
Ocean freight rates climb on tight capacity
Ocean freight rates climbed in August, with the Drewry World Container Index finishing the month at $4,473 per FEU, up 5.1% month over month and more than double prior year levels.
Key July-to-August changes impacting the U.S. market
- Transpacific capacity in August fell 9% month over month on Asia-to-U.S. East Coast (USEC) and 0.4% month over month on Asia-to-U.S. West Coast.
- Ten sailings were canceled in each of two consecutive weeks mid-month, tightening space ahead of general rate increases.
- Multiple carriers announced Panama Canal surcharges on Asia-to-USEC and Asia-to-Gulf Coast routes as the Panama Canal Authority implements precautionary measures to prepare for potential weather impacts, which took effect in early September.
- Bunker cost pressure and Emergency Fuel Surcharges reignited after the U.S.-Iran memorandum expired without a resolution.
What this means: Capacity discipline, not demand, was the driver of higher rates in August. Carriers pulled sailings from Asia-to-U.S. trades faster than seasonal demand eased, creating tighter capacity and supporting back-to-back double-digit weekly rate increases on the East Coast.
Surface transportation cools, but costs remain elevated
The throughline from August is that the U.S. surface market cooled without getting cheaper.
What’s happening: Spot rates retreated, tender rejections eased and seasonal demand faded, but contract rates advanced in every major equipment type, load-to-truck pricing accelerated at a historic pace and fuel delivered its single largest monthly increase of the year.
By the numbers:
- The national average price of a gallon of diesel in the United States surged above $6.
- The national average price for a gallon of gasoline is $4.29, up more than 40% since the conflict in the Middle East began.
- Fuel prices rose 14% in the past month and more than 60% in the past year.
- DAT monthly average spot rates fell for a second straight month, landing at $2.89 per mile for dry van and $3.54 per mile for flatbed, down 3.7% and 2.7% month over month, yet both remain roughly 42% above where they stood one year ago.
What this means: Carrier capacity continues to tighten and fuel costs remain high. The relief shippers are feeling in spot is a seasonal breather layered on top of a structurally tighter market.
Targeted cost pressure persists for raw materials
September continues the trend of targeted cost pressure rather than broad-based commodity inflation.
The key factors: Strong demand, tariff developments and supply chain conditions are keeping costs elevated across many metal-intensive products.
Across the categories:
- Copper moved to record highs on the London Metal Exchange as markets reacted to the possibility of Section 232 tariff expansion.
- Aluminum remains elevated and continues to be influenced by renewed trade tensions between the United States and Canada.
- Steel conduit lead times are improving but remain elevated, particularly for colored EMT, driven by increased demand from hyperscale projects.
- Resins remain mixed, although PVC pricing has strengthened in recent weeks.
- Lumber is relatively stable compared with other commodities, while crude oil remains an important watch item for freight, diesel and petrochemical-related costs.
Why it matters: Along with tariffs and freight, regional premiums, supplier availability, lead times and quote validity often have as much influence on project costs as the underlying commodity alone. Longer lead times may add sourcing or shipping costs, while shorter quote validity period narrow the window to secure a quoted price.
The bottom line: Expect continued volatility in metal-intensive, imported and project-driven categories. Copper-, aluminum- and steel-intensive products remain the areas most exposed to replacement-cost risk, while PVC products could face additional pricing pressure if demand remains strong or weather-related disruptions affect supply.
Tagged with Border States, supply chain