 PITTSBURGH — Wesco International announced its results for the third quarter of 2026.
“We are very pleased with our record third quarter results and carry positive business momentum into the fourth quarter,” said John Engel, Chairman, President, and CEO. “Once again, sales, backlog, operating profit, and earnings per share all increased double digits versus the prior year and achieved records that exceeded our expectations. We are particularly pleased with our free cash flow generation during the quarter which was strong given the sales growth we delivered. The past five consecutive quarters of double-digit sales growth demonstrate Wesco’s higher growth profile which extends well beyond our important data center positioning. Customer demand is strong across the rest of our diversified portfolio and end markets, with sales up high single-digits excluding data centers. Our customers continue to invest in major capital and infrastructure projects and increasingly rely on Wesco to manage their needs as we add more services to our portfolio and demonstrate the continued effectiveness of our One Wesco cross-selling strategy. Especially noteworthy, our backlog was up over 80%, to a new record level for each of our three business units.”
Engel concluded, “The power of our customer value proposition, global capabilities, and leading portfolio of products, services and solutions is clear as we continue to outperform the market. Our backlog growth is being fueled by multi-year customer commitments, as our large customers recognize our unique capabilities across the communications, security, electrical, utility and power markets. As a result, we are again significantly raising our full-year 2026 outlook reflecting our confidence in our continued strong execution. Given the positive market momentum that we are seeing, I’m bullish that Wesco will continue to outperform our markets and deliver superior value to our customers, suppliers, and shareholders to close out 2026 and in 2027.”
Net Sales
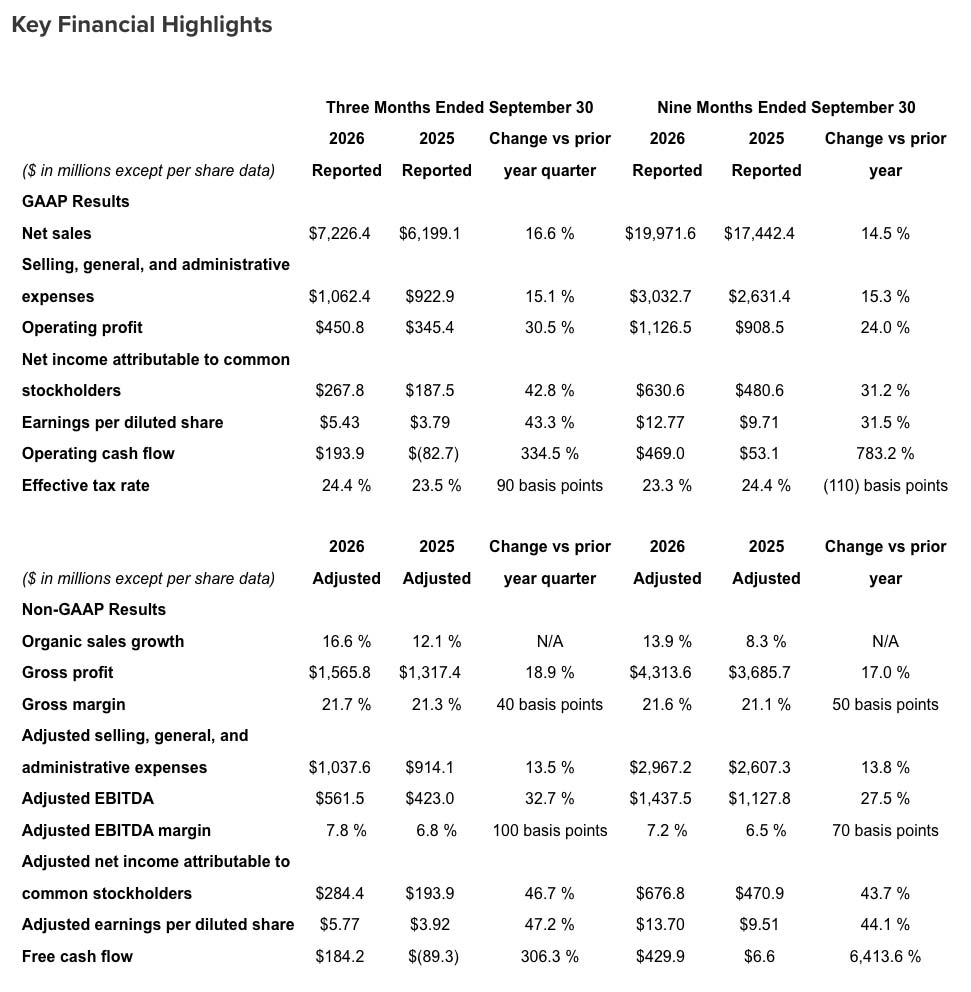
- On an organic basis, which removes the impact of the Newark Engineering Group (“Newark”) acquisition and differences in foreign exchange rates, sales for the third quarter of 2026 grew by 16.6%. The increase in organic sales reflects volume growth in all three segments (CSS, EES and UBS), as well as a favorable impact from changes in price. Sequentially, net sales increased 8.4% and organic sales grew by 8.5%. Record backlog at the end of the third quarter of 2026 was up by approximately 80% compared to the end of the third quarter of 2025.
- For the first nine months of 2026, organic sales grew by 13.9%. The increase in organic sales reflects volume growth in all three segments (CSS, EES and UBS), as well as a favorable impact from changes in price.
Gross Profit and Gross Margin
- The increase in gross margin for the three and nine months ended September 30, 2026 reflects improved gross margin in the EES and CSS segments.
Selling, General, and Administrative (“SG&A“) Expenses
- The increase in SG&A expenses for the third quarter of 2026 is primarily driven by an increase in commissions and incentives due to company performance, as well as higher salaries and benefits. SG&A expenses for the third quarter of 2026 include $24.8 million of digital transformation costs, compared to $8.8 million of digital transformation and restructuring costs for the third quarter of 2025. Adjusted for these costs, SG&A expenses were 14.4% and 14.7% of net sales for the third quarter of 2026 and 2025, respectively, reflecting improved operating cost leverage on the sales growth.
- The increase in SG&A expenses for the first nine months of 2026 is primarily driven by an increase in commissions and incentives due to company performance, as well as higher salaries and benefits. SG&A expenses for the first nine months of 2026 include $65.5 million of digital transformation costs, compared to $24.1 million for the first nine months of 2025. Adjusted for these costs, SG&A expenses were 14.9% of net sales for the first nine months of 2026 and 2025.
Adjusted EBITDA and Adjusted EBITDA Margin
- The increase in adjusted EBITDA and adjusted EBITDA margin for the third quarter of 2026 reflects higher sales, increased gross margin, and improved operating cost leverage. Sequentially, adjusted EBITDA margin increased 50 basis points.
- The increase in adjusted EBITDA and adjusted EBITDA margin for the first nine months of 2026 primarily reflects higher sales and increased gross margin.
Effective Tax Rate
- The higher effective tax rate for the three months ended September 30, 2026 is largely driven by a higher annual effective tax rate resulting from higher non-deductible compensation expense as compared to the prior year period.
- The lower effective tax rate for the nine months ended September 30, 2026 is largely driven by higher discrete income tax benefits relating to the exercise and vesting of stock-based awards and return to provision adjustments primarily attributable to lower U.S. tax on foreign income, partially offset by higher non-deductible compensation expense as compared to the prior year period.
Adjusted Earnings Per Diluted Share
- The increase in adjusted earnings per diluted share in the third quarter of 2026 reflects higher adjusted EBITDA, partially offset by a $32.8 million increase in the adjusted provision for income taxes.
- The increase in adjusted earnings per diluted share in the first nine months of 2026 reflects higher adjusted EBITDA, partially offset by a $47.4 million increase in the adjusted provision for income taxes and a $22.5 million increase in interest expense. The increase in interest expense was primarily driven by higher net term debt throughout the first nine months compared to the prior year, as well as a $10.0 million non-cash loss on extinguishment of debt, partially offset by the issuance of the 2031 Notes and 2034 Notes at lower rates as compared to the 2028 Notes, as well as lower rates on the amended accounts receivables securitization facility and the amended revolving credit facility. Additionally, the prior year period included the favorable impact of the Series A Preferred Stock redemption, partially offset by $27.3 million of preferred stock dividends.
Operating Cash Flow
- Net cash provided by operating activities for the third quarter of 2026 totaled $193.9 million compared to net cash used in operating activities of $82.7 million in the third quarter of 2025. The $276.6 million increase includes a $326.9 million impact from accounts payable, due to increased inventory purchases, as well as the timing of inventory purchases and payments to suppliers as compared to the prior year. A $227.3 million impact from changes in other current and noncurrent liabilities, primarily driven by deferred revenue due to advance payments from customers and milestone billings, and an increase in net income as adjusted for certain non-cash items versus the prior year also contributed to the increase. These increases were partially offset by a $169.3 million impact from inventories, primarily due to an increase in volume related to growth in large projects as compared to the prior year, a $93.6 million impact from changes in other current and noncurrent assets, primarily due to increases in supplier prepayments, and a $90.0 million impact from changes in trade accounts receivable, primarily due to increased sales growth in all three segments, as well as the timing of receipts from customers as compared to the prior year.
- Net cash provided by operating activities for the first nine months of 2026 totaled $469.0 million, compared to $53.1 million for the first nine months of 2025. The $415.9 million increase includes a $478.2 million impact from changes in accounts payable, due to increased inventory purchases, as well as the timing of inventory purchases and payments to suppliers as compared to the prior year. Other current and noncurrent liabilities additionally contributed to the increase, with a $397.7 million impact primarily driven by deferred revenue due to advance payments from customers and milestone billings. An increase in net income as adjusted for certain non-cash items also contributed to the increase in operating cash flows. These increases were partially offset by a $299.9 million impact from changes in trade accounts receivable and a $261.6 million impact from changes in other current and noncurrent assets. The impact from trade accounts receivable was primarily due to increased sales growth in all three segments, as well as the timing of receipts from customers as compared to the prior year, and the impact from other current and noncurrent assets was primarily due to increases in supplier prepayments. A $198.6 million impact from inventories also offset the increases, primarily due to an increase in volume related to increased growth in large projects as compared to the prior year.